£500,000 buys about €598,000 on the latest ECB rate. If you are a UK buyer with a deposit or completion due in Portugal in the next few weeks, don’t bet the whole transfer on Thursday’s Bank of England decision. A rate rise is already expected and largely priced in, so moving part of the money now and fixing the rest usually beats waiting for one big day.
I’m writing this on Tuesday 3 November, two days before the Bank of England announces its decision at 12:00 UK time on Thursday 5 November. I work with a lot of British buyers in Lagos and the wider Western Algarve, and the same question comes up every time sterling moves: should I send the money now, or wait? Here is how I think about it, with the numbers behind it.
Should I transfer my sterling now or wait for the Bank of England decision?
For most buyers, the honest answer is: don’t wait for Thursday with the whole amount. Economists polled by Reuters expect the Bank to raise Bank Rate from 3.75% to 4.0%, probably on a 7-2 vote, which would be its first rise since August 2023. Matthew Ryan at the currency firm Ebury calls that move “almost fully priced in”, and says the vote split and the guidance will matter more for sterling than the rise itself.
That is the key point. When a decision is expected, the pound has usually moved before the announcement, not after it. The surprise, in either direction, is what moves the rate on the day. A rise with cautious guidance can even leave sterling weaker than it was the morning before. Nobody can tell you which way Thursday goes, and I’m not going to pretend to.
What the pound has done since the summer
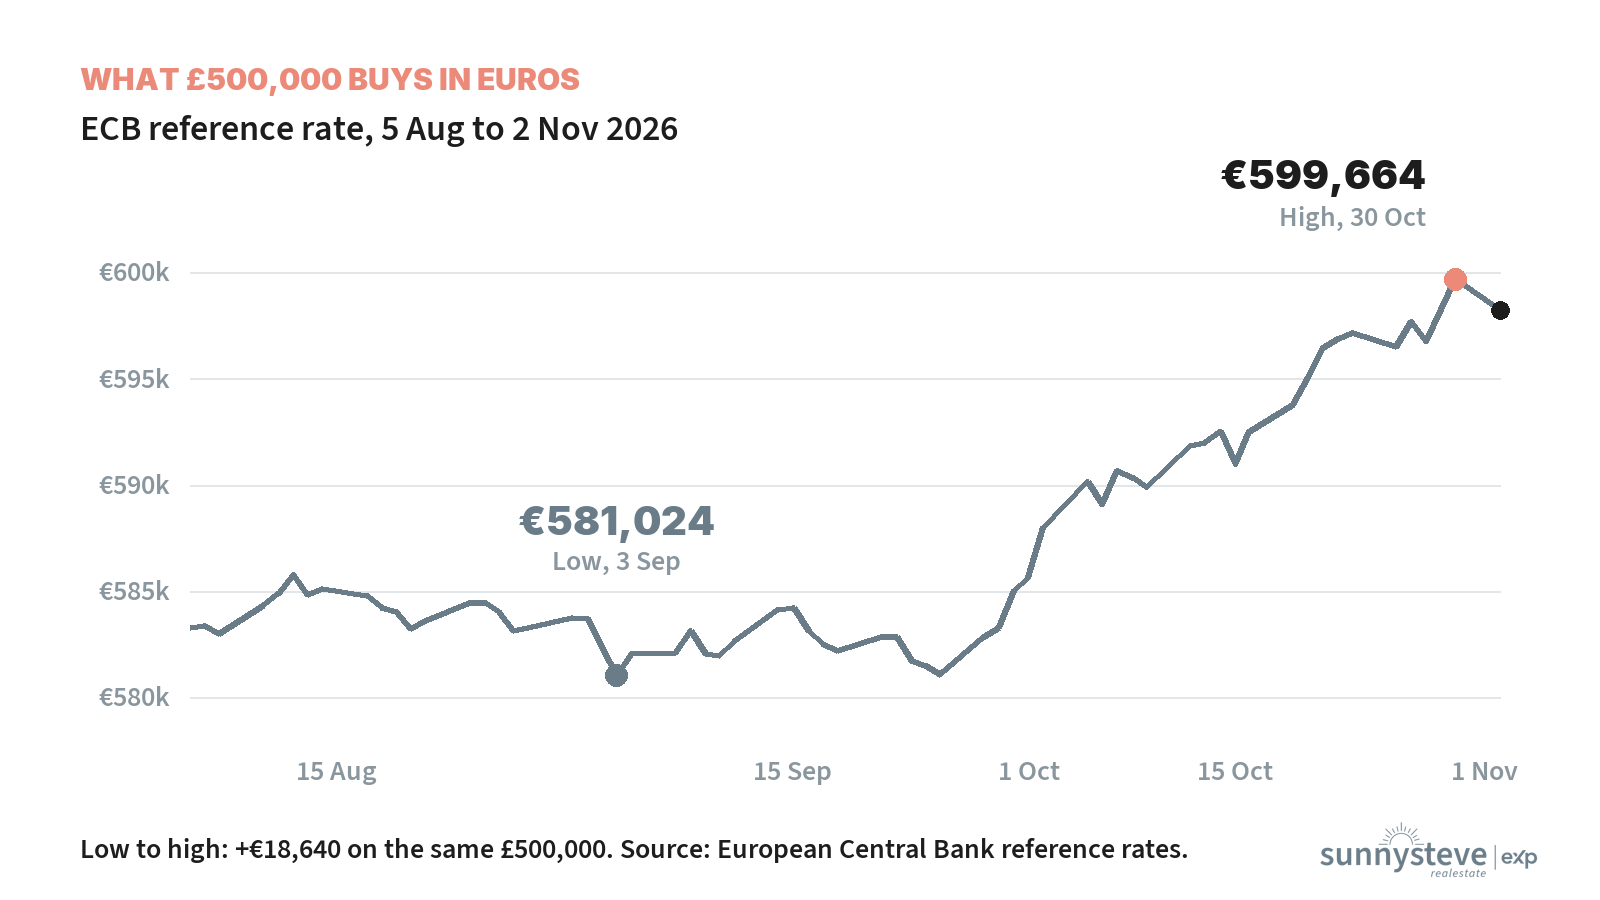
Sterling has had a good autumn against the euro. On the European Central Bank’s reference rate, £500,000 bought €581,024 on 3 September, the low of the last three months. By 30 October the same £500,000 bought €599,664, the high of that period. That is €18,640 more for the same pounds, and most of the gain came in October alone.
| ECB reference date | £1 buys | £500,000 buys |
|---|---|---|
| 5 August 2026 | €1.1666 | €583,294 |
| 3 September 2026 (3-month low) | €1.1620 | €581,024 |
| 1 October 2026 | €1.1713 | €585,665 |
| 30 October 2026 (3-month high) | €1.1993 | €599,664 |
| 2 November 2026 (latest) | €1.1965 | €598,229 |
What a 1%, 2% or 3% move means on a Lagos purchase
Percentages feel small until you put them on a house. At today’s rate, every 1% move in sterling changes a £500,000 transfer by about €6,000. Lagos asking prices averaged €4,772 per square metre in October, according to idealista, so a 3% swing is the price of nearly four square metres of a Lagos home.
| Move in GBP/EUR | Change on £500,000 | Lagos floor space at €4,772/m² |
|---|---|---|
| 1% | about €5,980 | about 1.3 m² |
| 2% | about €11,960 | about 2.5 m² |
| 3% | about €17,950 | about 3.8 m² |
If you already own in the Algarve and are weighing a sale against moving fresh sterling, it is worth knowing both sides of the sum: see what your home is worth today with the SunnySteve estimate.
Your options, side by side
| Option | What you get | What you risk | Who it suits |
|---|---|---|---|
| Transfer everything now | Today’s rate, close to the 3-month high, locked in | Missing any further rise after Thursday | Buyers who need certainty on the euro budget |
| Wait for Thursday | The chance of a better rate | A worse rate if the guidance disappoints; the rise is already expected | Buyers whose deadline is months away |
| Split the transfer | Part fixed now, part left open | Less upside, less downside | Most buyers with a date in the next few weeks |
| Forward contract | A rate agreed now, close to today’s, fixed for a set future date such as completion | You don’t benefit if sterling then rises | Buyers with a signed promissory contract and a known completion date |
What I tell UK buyers with a transfer due
I’m an estate agent, not a currency adviser, so treat this as what I see work for clients rather than financial advice. The buyers who sleep best are the ones who stop trying to pick the perfect day. They match transfers to the dates that matter in a Portuguese purchase: the deposit at the promissory contract (the CPCV), and the balance at the deed (the escritura).
- Know your euro number first. The price plus purchase taxes and fees, which are all paid in euros. Non-residents now pay a flat 7.5% IMT on homes, with two ways to claim part of it back later, as I explained in Portugal’s 7.5% IMT: there is no 1 September deadline. My closing cost calculator gives you the full figure in two minutes.
- Cover what is due soon. If a deposit falls due this month, fixing at least part of it now removes most of Thursday’s risk.
- Use a specialist, not your high-street bank. An FCA-authorised currency specialist will usually beat a bank’s rate and can set up a forward contract for completion day.
- Decide in advance. Write down the rate at which you would move the rest, then act when it comes, rather than watching the screen on Thursday.
If you are earlier in the process, my guide to buying property in Lagos as a foreigner walks through each stage, so you can see when the money actually has to land.
Frequently Asked Questions
Will the pound rise if the Bank of England raises rates on 5 November 2026?
Not necessarily. A rise from 3.75% to 4.0% is the consensus in the Reuters poll, and Ebury says it is almost fully priced in, so the vote split and the Bank’s guidance are likely to move sterling more than the rise itself. For a UK buyer in Lagos, that means Thursday is a coin toss, not a sure gain.
How much does a 1% move in the pound change a £500,000 property transfer to euros?
About €6,000 at the 2 November 2026 ECB rate, when £500,000 bought €598,229. At Lagos asking prices of €4,772 per square metre, that is roughly 1.3 square metres of a home.
Should I transfer my whole house deposit to Portugal at once?
What I suggest to UK buyers is to split it: fix enough to cover the deposit at the promissory contract now and leave the balance for the deed, sometimes fixed with a forward contract. That removes most of the risk of one bad day without giving up all the upside.
What is a forward contract when buying property in Portugal?
It is an agreement with a currency specialist to exchange a set amount of sterling on a future date, such as your completion at the notary, at a rate agreed now and close to today’s. It protects your euro budget if the pound falls, but you don’t benefit if it rises. Ask an FCA-authorised provider for the terms before you sign.
Do I pay Portuguese purchase taxes in euros?
Yes. IMT and stamp duty are paid in euros before the deed, so your currency plan has to cover them as well as the price. Non-residents now pay a flat 7.5% IMT on residential property in Portugal, and can reclaim the difference if they become tax resident within two years of the deed.
Buying in Lagos or the Western Algarve with sterling? Tell me what you are looking for, and I’ll help you time each payment around the dates that matter in a Portuguese purchase.